Peugeot RCZ Insurance Group: Complete UK Guide

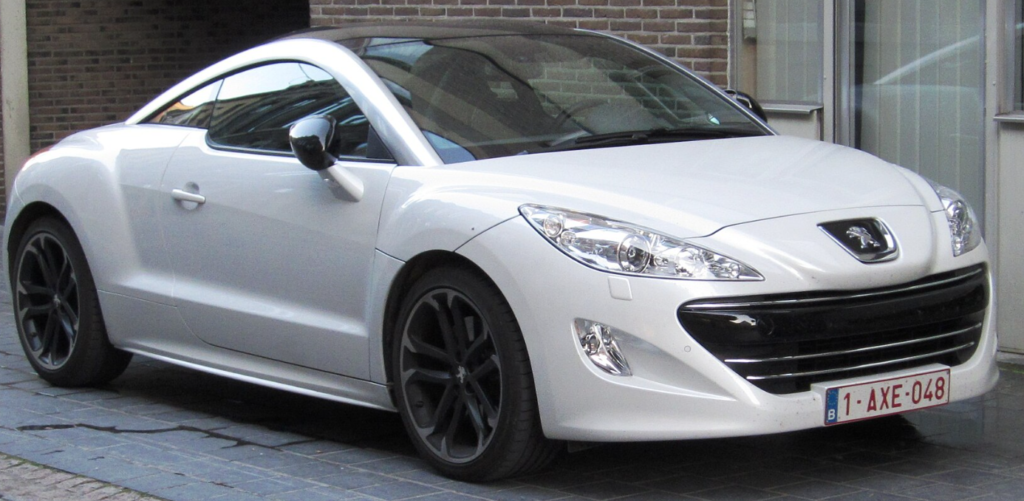
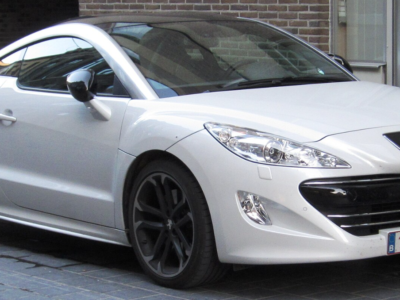
The Peugeot RCZ has always been one of those cars that looks more expensive and exotic than its badge might suggest. With its dramatic double-bubble roof, wide stance, frameless doors and low-slung coupé shape, it can easily look like something that should bring painful insurance premiums with it.
But how expensive is a Peugeot RCZ to insure, and what Peugeot RCZ insurance group should we expect?
In the UK, the answer depends heavily on the engine and trim. Late-model UK RCZ versions were officially rated from insurance group 27E at the lower end to group 42E for the high-performance RCZ R. That places most ordinary RCZ models somewhere in the middle-to-upper part of the UK's 1–50 insurance group system rather than among truly extreme performance cars. Peugeot's July 2015 UK technical specification confirms ratings ranging from 27E through 42E depending on the version.
Of course, the insurance group is only the beginning of the story. Two people can insure identical RCZs and receive wildly different quotations. Age, postcode, occupation, driving record, mileage and even where the car sleeps overnight can reshape the premium dramatically.
So let's unpack the Peugeot RCZ insurance groups properly and work out which versions are likely to be friendliest to our wallets.
Content in this publication
- What Insurance Group Is the Peugeot RCZ?
- Peugeot RCZ Insurance Group Explained Simply
- What Does the “E” Mean in 27E or 42E?
- Cheapest Peugeot RCZ to Insure
- Peugeot RCZ GT Insurance Group
- Peugeot RCZ 200 Insurance Group
- Peugeot RCZ Diesel Insurance Group
- Peugeot RCZ R Insurance Group
- Peugeot RCZ Insurance Group by Engine
- Why the RCZ Insurance Group Is Relatively High
- Does Insurance Group Determine the Premium?
- How Much Does Peugeot RCZ Insurance Cost?
- Can We Reduce Peugeot RCZ Insurance Costs?
- Do Modifications Affect RCZ Insurance?
- Is the Peugeot RCZ Expensive to Insure Compared With Normal Cars?
- Which Peugeot RCZ Is Best for Lower Insurance?
- Check the Exact RCZ Before Buying
- Final Thoughts on Peugeot RCZ Insurance Groups
- Frequently Asked Questions
What Insurance Group Is the Peugeot RCZ?
For UK-specification cars, the Peugeot RCZ insurance group generally falls between 27 and 42, although individual special editions and model years can vary.
Peugeot's 2015 UK specification gives the following official Association of British Insurers recommended ratings:
| Peugeot RCZ version | Insurance group |
|---|---|
| 1.6 THP 156 Sport Manual | 27E |
| 1.6 THP 156 GT Manual | 28E |
| 1.6 THP 156 Sport Automatic | 27E |
| 1.6 THP 156 GT Automatic | 28E |
| 2.0 HDi 163 Sport | 29E |
| 2.0 HDi 163 GT | 30E |
| 1.6 THP 200 Sport | 33E |
| 1.6 THP 200 GT | 34E |
| 1.6 THP 200 GT Line | 34E |
| 1.6 THP 270 RCZ R | 42E |
These figures come directly from Peugeot's July 2015 UK RCZ technical specification.
Independent current insurance references broadly support the same picture. Finder's UK RCZ data, updated in April 2026, places the model range between groups 27 and 42, while also showing certain special editions such as the Asphalt in higher groups than equivalent mainstream versions.
That means there isn't really one single "Peugeot RCZ insurance group." We need to know exactly which RCZ we're talking about.
Peugeot RCZ Insurance Group Explained Simply
UK cars are placed into insurance groups ranging from 1 to 50. In general, lower-numbered groups should be cheaper to insure than higher-numbered groups when all other factors are equal.
The Group Rating Panel, administered by Thatcham Research, assesses vehicles and provides these classifications. Insurers can use the ratings when calculating premiums, although they are not legally required to price every vehicle strictly according to its group.
Think of the group as the car's insurance starting point rather than its final price.
Group 27 does not mean we'll automatically pay a particular amount. Likewise, group 42 doesn't guarantee astronomical insurance.
Instead, the rating tells an insurer something about the underlying risk and potential claims cost associated with the vehicle.
Is Insurance Group 27 High?
Group 27 sits comfortably above the cheapest insurance categories.
A small city car aimed at first-time drivers might occupy a single-digit or low-teen insurance group. An RCZ starts much further up the ladder because we're dealing with a sporty coupé offering considerably more performance, larger wheels, specialist body panels and potentially more expensive accident repairs.
Still, group 27 isn't extreme.
For experienced drivers with a good record, a 1.6 THP 156 RCZ can therefore be surprisingly approachable from an insurance perspective.
Is Insurance Group 42 Expensive?
Group 42 is another story.
That's where the RCZ R sits in Peugeot's 2015 specification.
The R produces 270hp from its 1.6-litre turbocharged engine, versus 156hp in the entry petrol model. Peugeot listed a 0–62mph time of just 5.9 seconds and a 155mph maximum speed for the RCZ R.
Naturally, insurers see a very different proposition here.
It's like comparing a friendly house cat with the same animal after someone has fitted it with racing shoes.
What Does the “E” Mean in 27E or 42E?
Here's a small detail that's easy to overlook.
Nearly all the late RCZ insurance ratings shown in Peugeot's specification have an E after the number: 27E, 28E, 29E, 30E, 33E, 34E and 42E.
That's actually good news.
According to Thatcham's Group Rating System documentation, E means the vehicle exceeds the security requirements expected for a car of its type, allowing its group rating to be reduced.
Peugeot's 2015 RCZ specification also lists an ultrasonic alarm, immobiliser, deadlocks and locking wheel bolts as standard security equipment.
So that little letter isn't decorative. It tells us the RCZ performed favourably against the relevant security requirements used in its group assessment.
Cheapest Peugeot RCZ to Insure
If insurance cost is one of our biggest priorities, the 1.6 THP 156 Sport deserves attention.
Peugeot listed both the manual and automatic Sport versions at group 27E in its 2015 UK specification. Moving up to GT increased the rating slightly to 28E.
That gives us an interesting balance.
We still get the RCZ's distinctive styling and turbocharged petrol engine without jumping into the substantially higher groups occupied by the more powerful versions.
1.6 THP 156 Sport Insurance Group
Insurance group: 27E
This is essentially the gateway into RCZ ownership from an insurance standpoint.
With 156hp rather than 200hp or 270hp, performance is relatively restrained for a sporty coupé. Peugeot quoted 0–62mph in 8.3 seconds for the 156 manual in its 2015 specifications.
That's quick enough to feel enjoyable without moving into dedicated high-performance territory.
For buyers comparing used RCZ examples and worrying about annual running costs, this is arguably one of the first specifications worth obtaining quotes for.
Manual vs Automatic Insurance
Interestingly, Peugeot's late-model technical table shows the 156hp manual and automatic versions in the same groups according to trim: 27E for Sport and 28E for GT.
Don't assume this means their actual premiums will always match, though.
Insurers calculate quotations individually, and the exact vehicle registration remains more reliable than simply choosing an engine from a generic online table.
Peugeot RCZ GT Insurance Group
GT specification raises the RCZ's equipment level, and depending on the engine, its insurance group rises slightly too.
With the 156hp engine, the GT moves from the Sport's 27E to 28E.
Choose the 200hp petrol engine and the GT reaches 34E.
Go for the 2.0 HDi diesel and we're looking at 30E rather than the Sport diesel's 29E.
A one-group jump is unlikely to be the only deciding factor when choosing between Sport and GT, though. The driver's own risk profile can create a far larger price difference than one insurance group.
Peugeot RCZ 200 Insurance Group
The 200hp THP represents a noticeable step upward.
Peugeot rated the 1.6 THP 200 Sport at 33E, while GT and GT Line versions were rated 34E in the July 2015 specification.
That's six or seven groups above the entry 156 Sport.
Why?
Performance is one obvious reason. The 200hp manual was officially capable of reaching 62mph in 7.6 seconds, compared with 8.3 seconds for the 156 manual.
But insurance grouping involves more than raw horsepower.
You may be interested in reading Peugeot RCZ Weight: A Complete Guide to Kerb Weight and Specs
Repair cost, parts prices, replacement value and security can all influence how a vehicle is classified.
Is the THP 200 Much More Expensive to Insure?
Possibly—but we shouldn't assume that moving from group 27 to 33 will translate into a predictable percentage increase.
Insurance doesn't work like a staircase where every group adds another fixed £50 to the bill.
A 45-year-old driver with a long no-claims history might see a manageable difference. A 21-year-old driver could encounter a much larger jump.
That's why the group is best used for comparing vehicles before requesting real quotes rather than predicting the final premium.
Peugeot RCZ Diesel Insurance Group
The 2.0 HDi 163 sits in an interesting middle ground.
Peugeot listed the diesel as:
Sport: group 29E
GT: group 30E
So it's slightly higher than the 156hp petrol models but noticeably below the THP 200.
For drivers covering substantial annual mileage, that combination can make the HDi attractive. We're getting the distinctive RCZ body without immediately entering the mid-30 insurance groups occupied by more powerful petrol versions.
Again, we'd still want to compare actual quotations before buying.
Peugeot RCZ R Insurance Group
Now we reach the wild one.
The Peugeot RCZ R is insurance group 42E in Peugeot's 2015 UK specification.
That is a huge leap compared with the entry RCZ.
And it makes sense when we look beneath that curving roof.
The RCZ R produced 270hp from its 1.6-litre turbo engine and was the serious performance derivative of the range. Peugeot's own specification put its 0–62mph acceleration at 5.9 seconds.
Independent RCZ buying guidance similarly identifies the mainstream versions around groups 27–33, with the RCZ R climbing to group 42.
Why Is the RCZ R Group 42?
Power is part of it, but performance cars can also bring more expensive components.
The R wasn't simply an ordinary RCZ with a software tune. Peugeot equipped it as a distinct high-performance model, including model-specific elements such as its fixed rear spoiler, R wheels and upgraded sporting hardware.
An insurer has to think about what happens after something goes wrong—not simply how exciting the car feels on Sunday morning.
High-performance components can turn what looks like an ordinary bump into a much more expensive claim.
Peugeot RCZ Insurance Group by Engine
Sometimes the easiest way to understand the lineup is simply to step back and compare the engines.
The late-model hierarchy is clear:
156hp petrol → lowest groups
163hp diesel → slightly higher
200hp petrol → significant increase
270hp RCZ R → highest group
This makes engine choice particularly important when shopping for an RCZ.
A used RCZ R might appear surprisingly attainable compared with newer performance cars, but the purchase price tells only half the story. Insurance, tyres, servicing and specialist components continue to reflect the sort of car it was when new.
Why the RCZ Insurance Group Is Relatively High
The Peugeot badge might suggest mainstream running costs, but the RCZ itself isn't an ordinary Peugeot hatchback wearing a fancy jacket.
It's a dedicated sports coupé.
Group-rating assessments consider factors related to the financial risk associated with a vehicle. The AA notes that factors used in group ratings include aspects such as performance, replacement cost, repair cost and security.
That helps explain the RCZ's position.
Even a modest-powered RCZ features distinctive bodywork, a unique roof design, relatively large wheels and performance-focused mechanical components.
Repairing one after an accident can therefore be a different proposition from repairing a conventional family hatchback.
Repair Costs Matter More Than We Might Think
This is where insurance groups can surprise us.
We might naturally assume engine power determines everything.
It doesn't.
Insurance companies ultimately care about claims costs. A car that is relatively modest in performance but costly to repair can still receive a higher rating than expected.
The AA notes that vehicle repair costs rose significantly in recent years and that repair costs play an important role in group classification.
With an older specialist coupé like the RCZ, the availability and cost of certain body, trim and mechanical components may also matter to insurers when they calculate actual premiums.
No—and this point is crucial.
The insurance group describes the car.
Your quotation describes the combination of the car plus you plus your circumstances.
The AA specifically warns that insurers also consider factors including age, driving history, occupation, postcode, annual mileage, parking arrangements and vehicle use.
That's why someone can tell us, "My RCZ costs only £400 a year to insure," and that information may be practically useless for predicting our own premium.
Change the postcode, age or driving history and suddenly we're playing an entirely different game.
How Much Does Peugeot RCZ Insurance Cost?
There is no reliable universal annual price.
Current comparison data demonstrates why.
Finder's UK research uses sample quotations across multiple ages and postcode risk levels and shows substantial variation even for exactly the same RCZ specification. Its figures also show premiums changing dramatically according to age and location.
That's far more useful than pretending every group-27 RCZ costs roughly the same amount.
A 40-year-old living in a low-risk area with years of claim-free driving is a very different insurance customer from a newly qualified 20-year-old in a high-claim urban postcode.
Age Can Make a Huge Difference
Younger drivers frequently face significantly higher premiums because insurers use claims data associated with the driver's profile as well as the vehicle itself.
For that reason, the RCZ can be a tricky first car even in its lowest insurance group.
Group 27 is already well above the very low groups typically associated with inexpensive first cars.
An older or more experienced driver, however, may find the same RCZ surprisingly reasonable.
You may be interested in readingPeugeot RCZ Weight: A Complete Guide to Kerb Weight and SpecsYou may be interested in reading
 Toyota Corolla AE86 Engine Swap – The Ultimate Guide
Postcode Can Change Everything
Where the vehicle is normally kept matters too.
Insurers evaluate local claims patterns, theft exposure and other location-related risks. Finder's sample RCZ quotations demonstrate large differences between postcode areas even while keeping the driver's age and vehicle specification constant.
So when we're buying an RCZ, somebody else's quote is interesting—but our own quote is what matters.
Can We Reduce Peugeot RCZ Insurance Costs?
Absolutely. We can't manually move an RCZ from insurance group 34 to group 20, but we can influence several parts of the individual risk calculation.
Useful approaches include:
- Compare several insurers rather than automatically accepting a renewal.
- Get quotes for multiple RCZ engines and trims before buying the car.
- Build and protect a legitimate no-claims discount where appropriate.
- Choose realistic annual mileage rather than automatically estimating far above actual use.
- Consider a higher voluntary excess only if we could comfortably pay it after a claim.
- Keep the car somewhere secure when practical.
- Avoid undeclared performance or cosmetic modifications.
- Add experienced additional drivers only when they genuinely use the vehicle.
- Compare annual payment against monthly instalments, since instalment plans can carry additional costs.
- Request a quotation using the exact registration number of the RCZ we're considering.
That last point deserves emphasis.
When shopping for a used sports car, insurance should be checked before handing over a deposit.
Five minutes spent requesting a quote can prevent a nasty surprise after we've already fallen in love with those roof arches.
Do Modifications Affect RCZ Insurance?
They certainly can.
And the RCZ is exactly the kind of car owners enjoy modifying.
Aftermarket wheels, suspension changes, exhaust systems, remapping, body kits and engine upgrades may all need to be declared depending on the insurer.
Don't assume a modification is too small to matter.
Insurers define modifications differently, and failing to disclose relevant alterations can cause serious problems when making a claim.
The smartest approach is simple: tell the insurer what has changed and let them decide whether it affects the policy.
What About an ECU Remap?
A remap is particularly important because it can increase engine output.
If we've turned a 156hp RCZ into something materially more powerful, the original group rating doesn't magically describe the insurer's real-world risk anymore.
Declare it.
The same principle applies to aftermarket turbo components and substantial performance modifications.
Is the Peugeot RCZ Expensive to Insure Compared With Normal Cars?
Compared with a basic supermini? Usually, yes.
Compared with genuinely powerful sports cars? Not necessarily.
That's arguably one of the RCZ's attractions.
A standard 156hp Sport sitting in group 27E offers styling that still turns heads without immediately landing us in the insurance territory occupied by some much more expensive performance machines.
The RCZ R, however, changes the equation dramatically at group 42E.
In other words, saying "RCZ insurance is expensive" is too simplistic.
Which RCZ?
That single question can shift us by fifteen insurance groups.
Which Peugeot RCZ Is Best for Lower Insurance?
If keeping insurance exposure down is the priority, the 1.6 THP 156 Sport at group 27E is the obvious place to start researching.
The 156 GT follows closely at 28E, while the diesel Sport and GT sit at 29E and 30E respectively.
Drivers wanting 200hp move into groups 33E–34E, and the RCZ R makes the biggest leap to 42E.
But there's an important caveat.
Insurance group should never be the only reason we choose one used RCZ over another.
Service history, mechanical condition, mileage and previous maintenance can matter much more financially than saving one insurance group on paper.
A beautifully maintained group-30 RCZ may prove cheaper to own than a neglected group-27 example.
Check the Exact RCZ Before Buying
The figures in this guide provide an excellent reference, particularly for late UK models, but RCZ specifications changed during the car's production life and special editions can carry different ratings.
For example, current Finder data lists an RCZ Asphalt at group 35 while the RCZ R sits at 42.
So don't buy based solely on the words "RCZ GT" in an advertisement.
Check the year.
Check the engine.
Check whether it's manual or automatic.
Check the exact trim.
Most importantly, run the registration through an insurer or comparison service and obtain a real quotation.
That's the number that ultimately leaves our bank account.
Final Thoughts on Peugeot RCZ Insurance Groups
The Peugeot RCZ insurance group ranges roughly from 27 to 42 in the UK, with late-model official Peugeot ratings beginning at 27E for the 156hp Sport and reaching 42E for the 270hp RCZ R.
The sweet spot for drivers watching their insurance budget is therefore fairly obvious. The THP 156 sits at the bottom of the range, while the HDi remains relatively moderate. The THP 200 asks us to climb several groups, and the RCZ R belongs in another league entirely.
But an insurance group isn't an invoice.
It's more like the opening chapter.
Our age, address, driving history, mileage, occupation, parking arrangements and individual insurer can ultimately have a much greater influence on what we pay. The AA similarly advises drivers to treat group ratings as a comparison guide and obtain a quotation for the exact vehicle before buying.
That's especially true with the RCZ.
It's now a used sports coupé, so condition and specification vary considerably from car to car. Find a good one, check the registration with several insurers, and factor the premium into the overall ownership budget.
Then we can concentrate on the reason people buy an RCZ in the first place: that wonderfully unusual coupé sitting on the driveway.
Frequently Asked Questions
What insurance group is a Peugeot RCZ?
Most UK Peugeot RCZ versions fall between insurance groups 27 and 42. Late-model 156hp Sport versions are group 27E, while the high-performance 270hp RCZ R is group 42E. Exact ratings depend on engine, trim and model specification.
What insurance group is the Peugeot RCZ 1.6 THP 156?
In Peugeot's 2015 UK specification, the 1.6 THP 156 Sport is group 27E, while the GT is group 28E. This applies to both manual and automatic versions shown in that specification.
What insurance group is the Peugeot RCZ GT?
It depends on the engine. A late 156hp GT is 28E, the 2.0 HDi 163 GT is 30E, and the 200hp THP GT is 34E.
You may be interested in readingPeugeot RCZ Weight: A Complete Guide to Kerb Weight and SpecsYou may be interested in reading
Toyota Corolla AE86 Engine Swap – The Ultimate GuideYou may be interested in reading
 Does the Toyota Camry Have CVT Transmission?
What insurance group is the Peugeot RCZ R?
The 270hp Peugeot RCZ R is insurance group 42E according to Peugeot's UK technical specification. Its significantly greater performance helps explain why it sits far above standard RCZ models.
Is a Peugeot RCZ expensive to insure?
It can be more expensive than an ordinary small hatchback, but the answer depends heavily on the version and driver. Standard RCZ models begin around group 27, while the R reaches group 42. Your age, postcode, driving history, mileage and other personal factors can change the actual premium substantially.
If you want to know other articles similar to Peugeot RCZ Insurance Group: Complete UK Guide you can visit the category Blog.
Peugeot RCZ Reliability: How Dependable Is This Stylish Coupé?
Mazda CX-8 Reliability: How Dependable Is This 7-Seat SUV?
Is Infiniti QX60 a Good Car? A Complete Buyer’s Guide
Are Toyota Hilux Any Good? The Real-World Answer
Which Toyota Hilux Is the Most Reliable? The Best Years and Engines
Why Are Toyota Hilux So Tough? The Engineering Behind the Legend
Leave a Reply
More content of your interest